Posts

Taxability of Banking Industry in Pakistan
Image
The below discussion is based on the provisions of Income Tax Ordinance, 2001 only. BANKING BUSINESS Section 100A and Seventh Schedule of the Income Tax Ordinance, 2001 specify special provision relating to banking business. The relevant parts of the Ordinance are reproduced provisions relating below. SPECIAL PROVISIONS RELATING TO BANKING BUSINESS [Section 100A] Subject to sub-section (2), the income, profits and gains of any banking company as defined in clause (7) of section 2 and tax payable thereon shall be computed in accordance with the rules in the Seventh Schedule.  Subsectioon (1) shall apply to the profits and gains of the banking companies relevant to tax year 2009 and onwards. THE SEVENTH SCHEDULE  (See section 100A)   RULES FOR THE COMPUTATION OF THE PROFITS AND GAINS OF A BANKING COMPANY AND TAX PAYABLE THEREON . 1.   Income, profits and gains of a banking company shall be taken to be the balance of the i...
Impact of residential status on scope of Tax

CLICHED IMPACT OF RESIDENTIAL STATUS ON SCOPE OF INCOME [11] The residential status of a taxpayer (i.e., whether resident or non-resident) has important impact on the scope of his total income. In case of a resident, all incomes of a person (from wherever derived) are taxable in Pakistan whereas in the case of a non-resident person, only such incomes are chargeable to tax which are derived from or received within Pakistan. Scope of Total Income for Resident [11 (5)] In case of a resident all incomes, from whatever source derived, shall be included in the total income if during the tax year the income is: 1 Received in Pakistan; 2 Deemed to be received in Pakistan; 3. Accrued or arisen in Pakistan; 4 Deemed to accrue or arise in Pakistan; and 5. Accrued or arisen outside Pakistan. From the above it is construed that a resident person's total income has two components. which are: i) Pakistan-Source Income; and ii) Foreign-source incom...

PROCEDURE FOR TAKING CREDIT OF TAX PAID UNDER AMNESTY ACTS IN 2018 BUT DECLARATION NOT FILED

Image
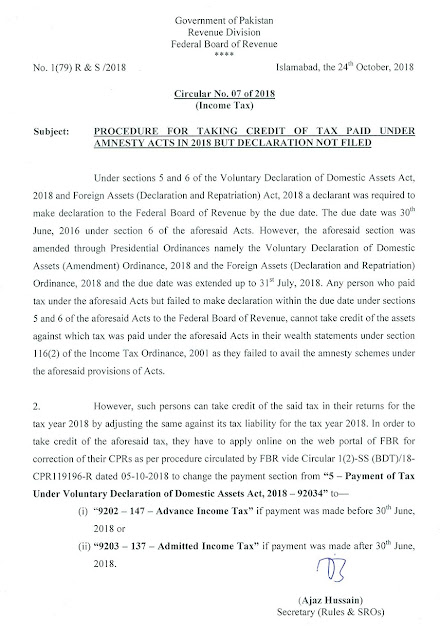
Government of Pakistan  Revenue Division  Federal Board of Revenue  No. I (79) R & S /20 I 8 Islamabad, the 24th October, 2018  Subject: Circular No. 07 of 2018 (Income Tax) PROCEDURE FOR TAKING CREDIT OF TAX PAID UNDER AMNESTY ACTS IN 2018 BUT DECLARATION NOT FILED  Under sections 5 and 6 of the Voluntary Declaration of Domestic Assets Act. 2018 and Foreign Assets (Declaration and Repatriation) Act, 2018 a declarant was required to make declaration to the Federal Board of Revenue by the due date. The due date was 30th June, 2016 under section 6 of the aforesaid Acts. However, the aforesaid section was amended through Presidential Ordinances namely the Voluntary Declaration of Domestic Assets (Amendment) Ordinance, 2018 and the Foreign Assets (Declaration and Repatriation) Ordinance, 2018 and the due date was extended up to 31st July, 2018. Any person who paid tax under the aforesaid Acts but failed to make declaration within the due date unde...

JURISDICTION AND DELEGATION OF POWERS [SECTIONS 209 to 213]

Image
Cliched JURISDICTION OF INCOME TAX AUTHORITIES [209] Provisions of the Income Tax Ordinance regarding jurisdiction of various tax authorities are discussed below:  1) The Board shall determine the jurisdiction of CCIRs, CIRs and Commissioners Appeals.  These persons shall perform such functions and powers as may be assigned to them by Board in respect of persons, classes of persons or areas.[209(1)]  2) The Board or the Chief Commissioner may transfer jurisdiction in respect of persons from one Commissioner to another.  3) The Board or the CCIR may assign an Officer of inland revenue the powers and function of the CIR. Under such a case the officer of inland Revenue shall have the jurisdiction in respect of such persons, classes of persons or areas as are specified in the order. Where an Officer of inland Revenue is delegated with the powers and function of a CIR, then he shall be treated as CIR. The CCIR shall make such orde...

Furnishing of information by banks under section 165A of the Income Tax Ordinance, 2001

UPDATE SBP turns down FBR request for data of account-holders Furnishing of information by banks under section 165A of the Income Tax Ordinance, 2001  Section 165A of the Income Tax Ordinance, 2001 inserted through the Finance Act, 2013 requires banking companies to provide information to the Federal Board of Revenue notwithstanding anything contained i:n any law for the time being in force. By virtue of amendments introduced in section 165A of the Ordinance through the Finance Act, 2018 banks are obliged to make arrangements for providing the following information to the Board in the prescribed form and manner:-  (i) List of persons containing particulars of cash withdrawals exceeding Rs. 50,000/- in a day and tax deduction thereon for filers and non-filers, aggregating to Rs. 1 million or more during each preceding calendar month.  (ii) A list containing particulars of deposits aggregating Rs. 10 million or more made during the preceding calendar mon...

Explanatory Cirlcular on 'SUPPLEMENTARY FINANCE ACT, 2018'

Image
GOVERNMENT O'F PAKISTAN REVENUE DIVISION FEDERAL BOARD OF REVENUE *****  C.No.4(69)1T-Budget/2018-(PT-I) Islamabad, the 24th October, 2018.  Circular No. 06 of 2018 Income Tax  SUBJECT:- FINANCE SUPPLEMENTARY (AMENDMENT} ACT, 2018 EXPLANATION OF IMPORT ANT AMENDMENTS MADE IN THE INCOME TAX ORDINANCE, 2001.  The Finance Supplementary (Amendment) Act, 2018 has brought about certain amendments in the Income Tax Ordinance, 2001. Some significant amendments are explained hereunder:-  1. Amendment in tax rates for individuals (a) Salaried Individuals Through the Finance Act, 2018 rates for both salaried and non-salaried individuals were unified and threshold of taxable income was increased from Rs.400,000/- to Rs.1,200,000/-. However, a nominal tax rate of Rs.1000/- was imposed on income(s) between Rs.400,000/- to Rs.800,000/- whereas a nominal tax rate of Rs.2000/- was imposed on income(s) between Rs.800,000/- to Rs.1,200,000/-.Moreover, a tax r...

Taxability of income from adsense in Pakistan

Image
The income from google adsense is taxable under Income Tax Ordinance, 2001. Misconceptions: - It is not eligible for immunity under Section 111; - It is not exempted under  IT Services category; PRODUCT ID: Adsense CLICK HERE TO  ORDER NOW This opinion is available on payment. Interested persons may contact the author on  zeeshanqureshi.email@gmail.com

Live Stream

Legal Advise

Taxation Training